


Hormuz Tanker Hit as Both Major Oil Routes Face Pressure
A tanker attack in the Strait of Hormuz comes as Saudi Arabia’s East-West oil pipeline is already shut, putting two major regional oil routes under pressure. With oil recently above $100, attention now turns to whether supply disruptions worsen and what Monday’s regional meeting means for Hormuz.
September 13, 2026
Hormuz Tanker Struck as Both Major Oil Routes Face Pressure
A ship was struck by a projectile in the Strait of Hormuz overnight, forcing its crew to evacuate after a fire broke out. The attack comes while Saudi Arabia’s East-West oil pipeline is already shut following drone strikes, putting pressure on two critical routes for moving Middle Eastern oil. The bigger question now is whether these disruptions remain contained or create another supply shock.
Watch Today’s Market Breakdown
See why the tanker attack matters beyond one vessel, how the East-West pipeline changes the oil-supply picture, and why Monday’s regional meeting is the next major catalyst.
Today’s Market Setup
The immediate story is a tanker attack in Hormuz. The broader market concern is that the incident comes while another major regional oil route is already unavailable, increasing the importance of what happens next across the region.
Tanker Struck in Hormuz
A projectile hit a ship in the Strait of Hormuz overnight and a fire forced the crew to evacuate. The concern extends beyond the vessel itself because Hormuz has already been largely disrupted by war.
East-West Pipeline Is Shut
Saudi Arabia’s East-West oil pipeline is also shut after drone strikes. The pipeline had been moving roughly four to five million barrels per day — approximately four to five percent of global supply.
Supply Risk Meets $100 Oil
Oil was already above $100 last week. With pressure now affecting both major regional routes, another supply shock could feed into fuel costs and inflation, keeping energy markets at the center of the broader economic picture.
What Matters From Here
The tanker attack explains what happened overnight. The next questions are about whether transportation pressure worsens and what Monday’s regional discussions mean for the future of Hormuz.
- Does pressure on both Hormuz and the East-West pipeline create a broader disruption to regional oil flows?
- Could another supply shock add renewed pressure to fuel costs and inflation after oil moved above $100 last week?
- What comes out of Monday’s meeting between regional countries over the future of the Strait of Hormuz?
The Headlines Are Only the First Step
The free Market Preview explains why the tanker attack matters and why having both major oil routes under pressure changes the market setup. The members-only Daily Market Brief goes deeper into the catalysts, risks, confirmation signals and developments worth monitoring as the region approaches Monday’s meeting.
See What Members GetInside Today’s Members-Only Daily Market Brief
- The developments that could show whether pressure on the region’s two major oil routes is stabilizing or becoming a larger supply problem.
- The signals worth monitoring around oil after prices moved above $100 last week.
- Why additional disruption could matter for fuel costs and the broader inflation picture.
- What Monday’s regional meeting could change about the market’s focus on the future of Hormuz.
Go Beyond the Headlines
The public Market Preview tells you what happened. The Generational Wealth Community is designed for investors who want to understand what deserves attention next, what could confirm the current market setup, what risks could change it and which developments deserve continued monitoring. We don’t chase hype, we decode the market.
Unlock the Daily Market BriefEducational market research designed to help investors understand the setup — not chase headlines.
Your pathway from knowledge to legacy. We don’t chase hype, we decode the market.
Stay Ahead of What Matters Next
Follow the oil-supply, inflation and regional developments that could determine whether today’s disruption remains contained or becomes a broader market issue.
Join the Generational Wealth Community
Oil Jumps 5% as 10-Year Yield Hits 4.81% and Gold Falls
Oil surged as renewed fighting near the Strait of Hormuz pushed energy prices higher while the 10-year Treasury yield reached about 4.81%. Gold’s decline reveals the bigger market tension as investors weigh geopolitical risk against higher yields, a stronger dollar and the next test from U.S. labor data.
September 2, 2026
Oil Jumps 5% as Treasury Yields Hit 4.81% — So Why Is Gold Falling?
Oil surged after renewed U.S.-Iran fighting near the Strait of Hormuz, pushing Brent to $94.65 Tuesday and briefly near $97 overnight. At the same time, the 10-year Treasury yield reached about 4.81%, its highest since 2023. Yet gold moved the opposite direction, falling to a more than three-week low as higher yields and a stronger dollar outweighed safe-haven demand. Now labor data could test the entire setup.
Watch Today’s Market Breakdown
See how the Hormuz oil shock is feeding into inflation expectations, Treasury yields, stock valuations and gold ahead of the ADP employment report.
Today’s Market Setup
The market is dealing with one connected chain of pressure: geopolitical risk is lifting oil, higher oil is keeping inflation concerns alive, and rising rate expectations are pushing Treasury yields higher.
Oil Surges on Hormuz Risk
Brent settled Tuesday at $94.65, up 4.6%, while WTI gained 5.2%. Brent then briefly touched $97 overnight before easing near $95. Renewed U.S.-Iran fighting near Hormuz is keeping supply risk at the center of the inflation outlook.
Treasury Yields Reach New Highs
The 10-year Treasury yield reached about 4.81%, its highest since 2023, while the 2-year climbed near 4.41%. Higher energy costs can keep inflation elevated, strengthening the market’s focus on whether the Federal Reserve may need to raise rates again.
Gold Breaks the Safe-Haven Pattern
Spot gold fell near $4,324, a more than three-week low, despite the geopolitical tension. Higher Treasury yields and a stronger dollar outweighed safe-haven demand, showing why geopolitical risk alone has not been enough to push gold higher.
What Matters From Here
Oil, rates, stocks and gold are now reacting to the same inflation question. The next test is whether incoming labor data reinforces the higher-rate narrative or begins to challenge it.
- Does the ADP private-payrolls report strengthen the case for another Federal Reserve rate hike, or complicate the market’s current expectations?
- Can oil remain near current levels if fighting around the Strait of Hormuz continues to threaten supply?
- Will higher Treasury yields and a stronger dollar continue to outweigh safe-haven demand for gold?
The Headlines Are Only the First Step
The free Market Preview explains why oil, Treasury yields, stocks and gold are moving the way they are. The members-only Daily Market Brief goes deeper into the catalysts, risks, confirmation signals and developments worth monitoring as the market determines whether this inflation-and-rates pressure continues.
See What Members GetInside Today’s Members-Only Daily Market Brief
- The developments that could confirm whether the current oil-driven inflation pressure is continuing or beginning to ease.
- How the ADP employment report fits into the market’s changing expectations for Federal Reserve policy.
- The Treasury-yield signals worth following as the 10-year trades around its highest level since 2023.
- What gold’s weakness may reveal about the competition between safe-haven demand, higher yields and a stronger dollar.
- The next developments that could change the relationship between energy prices, interest rates and stock valuations.
Go Beyond the Headlines
The public Market Preview tells you what happened and why investors are paying attention. The Generational Wealth Community is designed for investors who want to understand what deserves attention next, what could confirm the current market setup, what risks could change it and which developments deserve continued monitoring. We don’t chase hype, we decode the market.
Unlock the Daily Market BriefEducational market research designed to help investors understand the setup — not chase headlines.
Your pathway from knowledge to legacy. We don’t chase hype, we decode the market.
Stay Ahead of What Matters Next
Follow the catalysts that matter as markets weigh oil near $95, Treasury yields around 4.81%, gold weakness and the next test from U.S. labor data.
Join the Generational Wealth Community
Rate-Hike Odds Hit 66% as Oil Hits $92 and Yields Rise
Rate-hike odds have climbed to 66% as oil trades near $92 and the 10-year Treasury yield reaches its highest level since January 2025. With gold falling and major employment reports approaching, the next question is whether labor data confirms the market’s latest repricing or challenges it.
September 1, 2026
Rate-Hike Odds Jump to 66% as Oil Hits $92 and Treasury Yields Rise
Rate-hike expectations climbed to 66% as oil moved near $92 and the 10-year Treasury yield reached about 4.78%, its highest level since January 2025. Gold is falling at the same time, showing how rising yields are reshaping the inflation trade. Now the market turns to labor data to determine whether this repricing has more room to run.
Watch Today’s Market Breakdown
See how higher oil, rising Treasury yields and shrinking rate-cut expectations are converging ahead of this week’s critical labor data.
Rate-Hike Odds Jump to 66% — Oil $92, Yields 4.78%, Gold Falling Watch Today’s Market BriefingToday’s Market Setup
The market is repricing around three connected pressures: higher energy costs, higher Treasury yields and growing expectations that the Federal Reserve may need to remain restrictive.
Rate-Hike Odds Reach 66%
The implied probability of a rate increase climbed to 66%, extending the repricing that followed Fed Chair Kevin Warsh’s hawkish message Friday. The 10-year Treasury yield is around 4.78%, its highest since January 2025, reinforcing the signal coming from interest-rate markets.
Oil Near $92 Keeps Inflation in Focus
Oil is near $92 after renewed U.S.-Iran fighting revived supply concerns around the Strait of Hormuz. The Strategic Petroleum Reserve also fell to 286.6 million barrels last week, its lowest level since November 1982, leaving a smaller emergency cushion as crude rises.
Higher Yields Pressure Gold
Spot gold fell about 1.2% to around $4,394 even as inflation concerns remain elevated. Higher Treasury yields increase the opportunity cost of holding non-yielding bullion, creating a market where inflation fears and rising interest rates are pulling gold in opposite directions.
What Matters From Here
Oil, yields and rate expectations are all moving in the same direction. The next question is whether incoming labor data reinforces that alignment or begins to challenge it.
- Does Wednesday’s ADP employment report reinforce the market’s higher-rate expectations before the more important Friday jobs report?
- Can oil remain near current levels if supply concerns around the Strait of Hormuz persist?
- Does Friday’s August jobs report strengthen the case behind the 66% rate-hike probability, or force markets to reconsider the current repricing?
The Headlines Are Only the First Step
The free Market Preview explains why oil, Treasury yields and rate-hike expectations are moving together. The members-only Daily Market Brief goes deeper into the catalysts, risks, confirmation signals and developments worth monitoring as labor data tests the market’s current assumptions.
See What Members GetInside Today’s Members-Only Daily Market Brief
- The developments that could reinforce or challenge the market’s current 66% rate-hike probability.
- How labor-market data fits into the Fed repricing now taking place across Treasury yields.
- The oil-supply risks worth monitoring as crude trades near $92 and the Strategic Petroleum Reserve sits at a multi-decade low.
- What gold’s decline may reveal about the balance between inflation concerns and rising real returns available elsewhere.
- The next catalysts that could confirm whether today’s higher-oil, higher-yield setup continues or begins to change.
Go Beyond the Headlines
The public Market Preview tells you what happened and why investors are paying attention. The Generational Wealth Community is built for investors who want to understand what deserves attention next, what could confirm the current setup, what risks could change it and which developments deserve continued monitoring. We don’t chase hype, we decode the market.
Unlock the Daily Market BriefEducational market research designed to help investors understand the setup — not chase headlines.
Your pathway from knowledge to legacy. We don’t chase hype, we decode the market.
Stay Ahead of What Matters Next
Follow the catalysts that matter as markets weigh oil near $92, Treasury yields around 4.78%, higher rate-hike expectations and this week’s employment reports.
Join the Generational Wealth Community
Oil Tops $90 After Hormuz Strike as Hike Odds Hit 57%
Oil moved above $90 after a U.S. strike near the Strait of Hormuz put one of the world’s most important energy routes back in focus. With September rate-hike odds now at 57%, the next question is whether higher energy prices or Friday’s jobs report has the bigger impact on Fed expectations.
August 31, 2026
Oil Blows Past $90 After Hormuz Strike — Rate Hike Odds Jump to 57%
Oil moved above $90 after American forces struck Iranian launchers near the Strait of Hormuz, putting one of the world’s most important energy routes back at the center of the market. The complication is that inflation pressure is already colliding with rising expectations for a September Fed rate increase. Now investors have two major risks to track: energy disruption and Friday’s jobs report.
Watch Today’s Market Breakdown
See why the Hormuz strike pushed oil above $90, how it connects to inflation and rate expectations, and why Friday’s jobs report matters.
Oil Blows Past $90 After Hormuz Strike — Rate Hike Odds Jump to 57% Watch Today’s Market BriefingToday’s Market Setup
The market is dealing with a renewed geopolitical oil shock while interest-rate expectations are already moving in a more restrictive direction.
Hormuz Risk Sends Oil Above $90
American forces struck two Iranian launchers on Larak Island after officials said Revolutionary Guard forces were preparing rockets carrying sea mines into the Strait of Hormuz. Iran then attacked American forces in Jordan. Brent futures climbed about 2% overnight and moved above $90 a barrel.
Oil Adds to the Inflation Problem
Fed Chair Kevin Warsh said Friday that the Fed still has work to do if inflation is not moving clearly toward 2%. Markets raised the implied probability of a September rate increase to 57%, while the two-year Treasury yield is near 4.34% after rising almost 12 basis points Friday.
Friday’s Jobs Report Becomes the Next Test
President Trump said Venezuelan oil from the new American agreement will help refill the Strategic Petroleum Reserve, but additional Venezuelan production requires investment. That leaves the immediate Hormuz risk unresolved while markets wait to see whether Friday’s labor data changes rate-hike expectations.
What Matters From Here
Oil above $90 explains what changed overnight. The more important issue now is how long the pressure lasts and whether it reinforces the Fed’s inflation concerns.
- Does the Strait of Hormuz remain disrupted enough to keep upward pressure on oil, or does the immediate geopolitical risk begin to ease?
- Does higher oil strengthen the inflation argument enough to keep September rate-hike expectations elevated?
- Could a weaker-than-expected jobs report on Friday cool those expectations even if energy prices remain under pressure?
The Headlines Are Only the First Step
The free Market Preview explains why oil, inflation and interest-rate expectations are colliding today. The members-only Daily Market Brief goes deeper into the catalysts, risks, confirmation signals and developments worth monitoring as the Hormuz story and Friday’s jobs report reshape the market setup.
See What Members GetInside Today’s Members-Only Daily Market Brief
- The Hormuz developments that could strengthen or weaken the current oil-supply risk.
- How renewed energy inflation interacts with the market’s 57% September rate-hike probability.
- Why the two-year Treasury yield matters as investors reassess the Fed’s next move.
- What Friday’s jobs report could change about the current interest-rate setup.
- How Venezuela’s longer-term supply story fits against the immediate geopolitical pressure in the Strait of Hormuz.
Go Beyond the Headlines
The public Market Preview tells you what happened and why investors are paying attention. The Generational Wealth Community is built for investors who want to understand what deserves attention next, what could confirm the current setup, what risks could change it, and which developments deserve continued monitoring. We don’t chase hype, we decode the market.
Unlock the Daily Market BriefEducational market research designed to help investors understand the setup — not chase headlines.
Your pathway from knowledge to legacy. We don’t chase hype, we decode the market.
Stay Ahead of What Matters Next
Follow the catalysts that matter as markets weigh renewed Hormuz risk, oil above $90, higher rate-hike expectations and Friday’s jobs report.
Join the Generational Wealth Community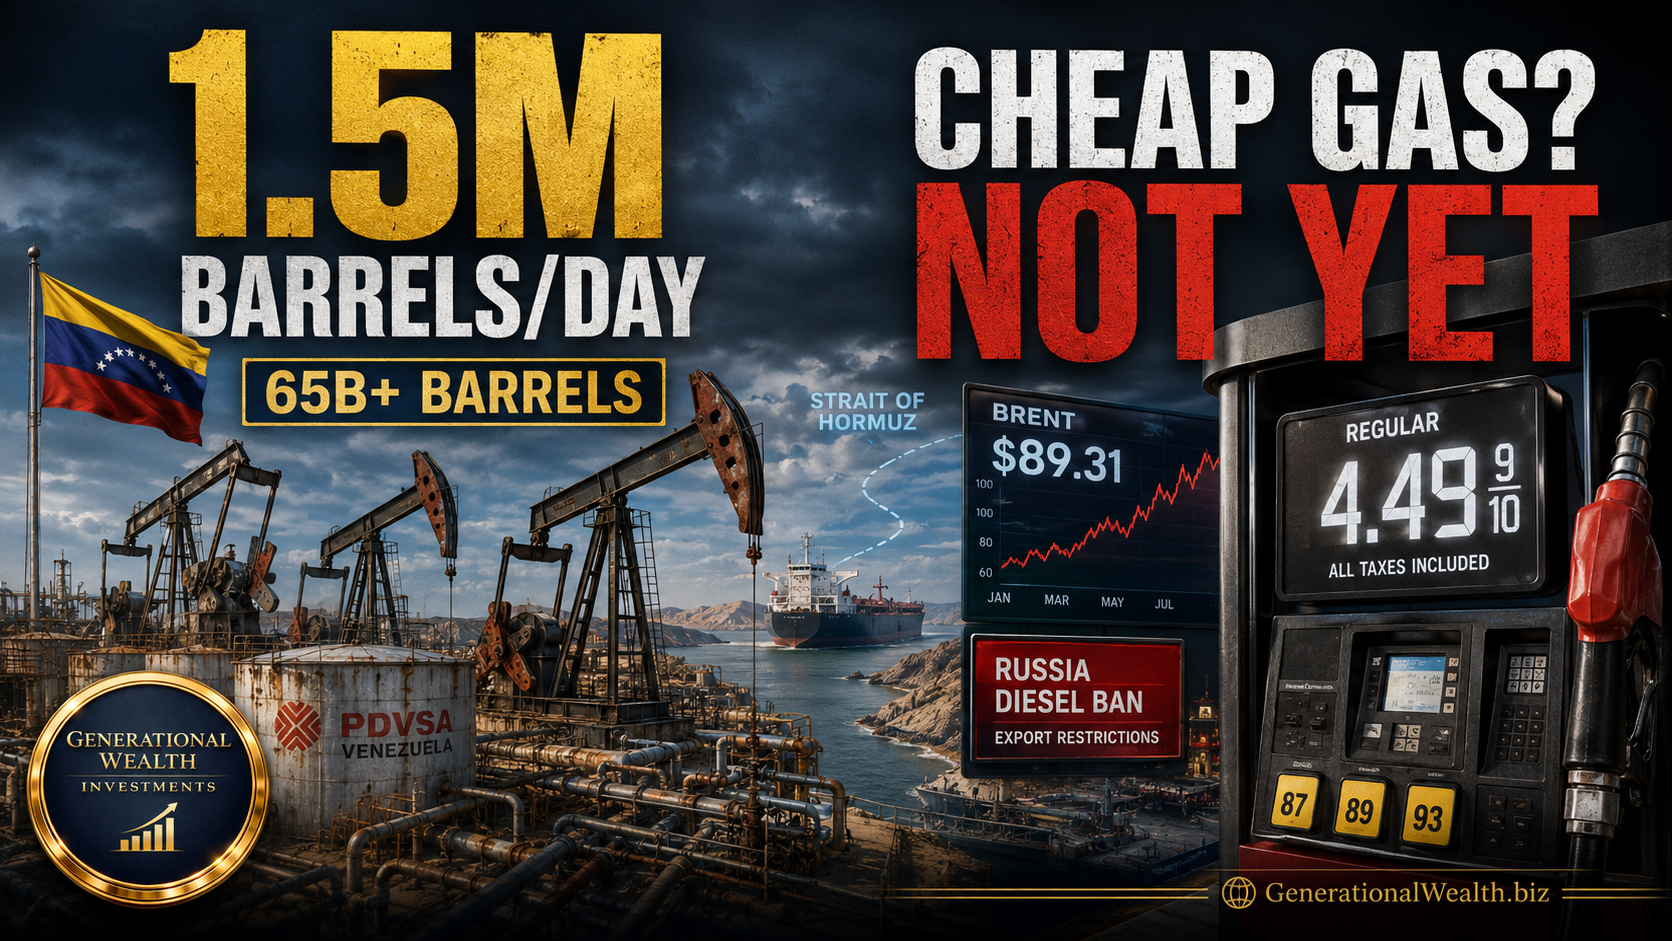
Venezuela’s 1.5M-Barrel Oil Deal: Why Gas Won’t Drop Yet
Venezuela’s new U.S. oil project targets more than 1.5 million barrels a day, but years of underinvestment mean those barrels may not reach the market quickly. At the same time, Russia’s diesel export ban and shifting Strait of Hormuz flows are creating a much more complicated near-term oil setup.
August 30, 2026
Venezuela Targets 1.5M Barrels a Day — Why Cheap Gas Isn’t Here Yet
Venezuela’s new U.S. oil project is targeting more than 1.5 million barrels a day and covers over 65 billion barrels of proven reserves. But years of underinvestment mean substantial new production could still take years, while Russia’s diesel export ban is tightening fuel availability now. The opportunity is enormous — but timing is what matters.
Watch Today’s Market Breakdown
See why Venezuela’s massive oil agreement does not automatically mean cheaper gasoline now, and how Russia, Hormuz and Brent crude complicate the near-term setup.
Today’s Market Setup
The oil market is balancing enormous potential future supply from Venezuela against infrastructure problems and fuel constraints that remain important right now.
Venezuela Targets 1.5M Barrels a Day
Venezuela says the 25-year bilateral project will develop 17 strategic oilfields and targets more than 1.5 million barrels of daily production. The original agreement covers more than 65 billion barrels of proven reserves, creating substantial long-term supply potential.
Infrastructure Is the Near-Term Constraint
Venezuela’s oil industry has suffered from years of underinvestment. Experts cited in the supplied research say major repairs could take years before production rises substantially, meaning headline production targets and actual new barrels may arrive on very different timelines.
Russia Keeps Pressure on Fuel Supply
Russia extended its diesel export ban through September 30 after drone attacks left several refineries offline. Meanwhile, Brent settled Friday at $89.31, down more than 5% for the week as traders weighed improving Hormuz flows and a more hawkish Federal Reserve.
What Matters From Here
The size of Venezuela’s agreement is clear. The bigger issue is how quickly the long-term supply story begins turning into actual production while current fuel constraints remain in place.
- How quickly can Venezuela repair infrastructure and translate the 1.5-million-barrel-a-day target into meaningful new production?
- Does Russia’s diesel export ban offset some of the near-term pressure lower from improving oil flows through the Strait of Hormuz?
- Do the new company agreements expected next week, including talks involving Chevron, begin moving the project from announcement toward execution?
The Headlines Are Only the First Step
The free Market Preview explains why Venezuela’s oil agreement matters and why it does not immediately solve today’s fuel constraints. The members-only Daily Market Brief goes deeper into the catalysts, risks, confirmation signals, and developments worth monitoring as this supply story moves from announcement toward execution.
See What Members GetInside Today’s Members-Only Daily Market Brief
- The developments that could show whether Venezuela’s 1.5-million- barrel-a-day target is beginning to move from headline to execution.
- Why the timing of infrastructure repairs matters to the long-term supply narrative and expectations around future production.
- How Russia’s diesel restrictions and improving Strait of Hormuz flows are pulling the near-term fuel market in opposite directions.
- What the company agreements expected next week could clarify about the pace and credibility of Venezuela’s oil expansion.
Go Beyond the Headlines
The public Market Preview tells you what happened and why investors are paying attention. The Generational Wealth Community is designed for investors who want to understand what deserves attention next, what could confirm the current setup, what risks could change it, and which developments deserve continued monitoring. We don’t chase hype, we decode the market.
Unlock the Daily Market BriefEducational market research designed to help investors understand the setup — not chase headlines.
Your pathway from knowledge to legacy. We don’t chase hype, we decode the market.
Stay Ahead of What Matters Next
Follow the catalysts and risks that matter as Venezuela moves toward new company agreements while Russia, Hormuz and infrastructure constraints continue shaping the oil-market setup.
Join the Generational Wealth Community
Brent Crude Falls to $86 as Hormuz Talks Lower Yields
Brent crude has dropped more than 6% in two sessions as Iran and Oman discuss a temporary shipping corridor through the Strait of Hormuz. Treasury yields are falling too, but limited vessel traffic and this morning’s PCE inflation report will test whether the relief can hold.
August 26, 2026
Brent Crude Falls to $86 as Hormuz Reopening Talks Begin — Yields Drop Too
Brent crude has fallen more than 6% in two sessions as Iran and Oman discuss a temporary shipping corridor through the Strait of Hormuz and an agreement to clear mines. Oil is now around $86 a barrel, potentially easing a major inflation pressure as Treasury yields fall. But Hormuz is not fully open, and this morning’s PCE inflation report is the next major test.
Watch Today’s Market Breakdown
See why Hormuz reopening talks are moving oil, how falling crude connects to Treasury yields, and why PCE inflation matters next.
Today’s Market Setup
The market is reacting to the possibility that one of the world’s most important oil routes could begin reopening, but the physical shipping data still shows significant disruption.
Brent Crude Drops Toward $86
Brent settled down nearly 4% Tuesday and fell again this morning to around $86 a barrel. Iran and Oman are discussing a temporary shipping corridor through Hormuz, where roughly one-fifth of the world’s traded oil moved before the war.
Treasury Yields Move Lower
Lower oil can reduce a major source of inflation pressure. The 10-year Treasury yield fell about eight basis points Tuesday to roughly 4.63%, while the 30-year declined to around 5.16%. The S&P 500 gained about 0.3% and the Nasdaq rose roughly 0.7%.
Hormuz Is Still Far From Normal
Only five commodity vessels reportedly transited the strait Tuesday, far below recent normal levels. A tanker was also disabled near Hormuz after an unidentified projectile strike. The reopening narrative is developing faster than normal shipping activity has returned.
What Matters From Here
Falling oil and yields have changed the market setup, but the next signals will determine whether that relief is reinforced or challenged.
- Do the Hormuz discussions translate into meaningfully higher vessel traffic through the strait?
- Does this morning’s PCE inflation report reinforce the easing in oil and Treasury yields, or challenge it with a hotter reading?
- Can the stock-market response hold if shipping disruptions remain significant even as crude prices continue falling?
The Headlines Are Only the First Step
The free Market Preview explains why oil, Hormuz and Treasury yields matter today. The members-only Daily Market Brief goes deeper into the catalysts, risks, confirmation signals and developments worth monitoring as investors evaluate whether the current relief is becoming more durable.
See What Members GetInside Today’s Members-Only Daily Market Brief
- The shipping and vessel-flow developments that could confirm or weaken the Hormuz reopening narrative.
- How falling crude, PCE inflation and Treasury yields fit together in the current market setup.
- What continued disruption near the strait could mean for the relief already appearing across oil, bonds and equities.
- The next developments worth monitoring as markets test whether lower inflation pressure can persist.
Go Beyond the Headlines
The public Market Preview tells you what happened and why investors are paying attention. The Generational Wealth Community is designed for investors who want to understand what deserves attention next, what could confirm the current setup, what risks could change it, and which developments deserve continued monitoring. We don’t chase hype, we decode the market.
Unlock the Daily Market BriefEducational market research designed to help investors understand the setup — not chase headlines.
Your pathway from knowledge to legacy. We don’t chase hype, we decode the market.
Stay Ahead of What Matters Next
Follow the catalysts, risks and confirmation signals that matter as markets evaluate falling oil, Hormuz shipping conditions, inflation and Treasury yields.
Join the Generational Wealth Community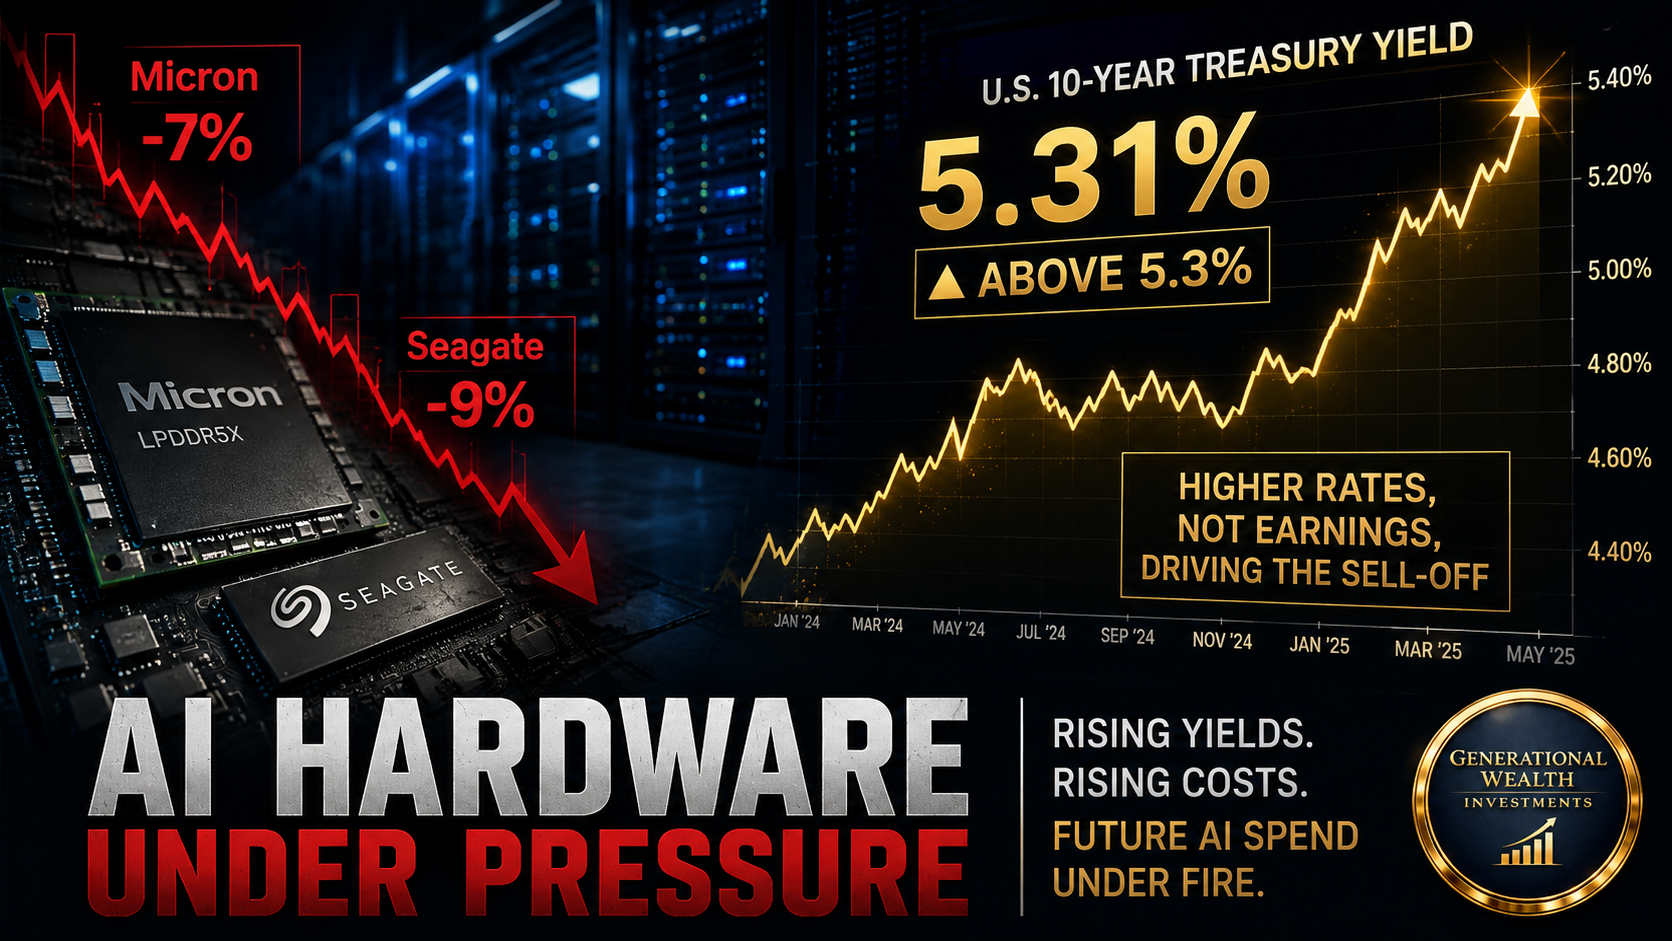
Micron Fell 7% as Treasury Yields Pressure AI Hardware
Micron, Seagate, and SanDisk were hit hard even without bad earnings or company-specific news. The real pressure came from rising long-term Treasury yields, just as investors begin questioning the enormous future cost of the AI buildout.
August 19, 2026
Micron Fell 7%, Seagate 9% — The Real Reason Isn't Earnings
Micron fell 7% yesterday while SanDisk and Seagate each dropped about 9% — without bad earnings or company-specific news driving the move. The pressure came as the 30-year Treasury yield climbed above 5.3%, a 19-year high, hitting stocks valued on profits far into the future. Now investors are watching whether higher yields, enormous future AI commitments, and today’s Fed minutes extend the pressure.
Watch Today’s Market Breakdown
See why rising long-term rates hit memory stocks so hard, how future AI spending commitments add to the pressure, and why today’s Fed minutes matter next.
Today’s Market Setup
The selloff was not simply another bad day for technology. Rising borrowing costs hit the market’s most rate-sensitive AI names while much of the broader market held up better.
Higher Yields Hit AI Hardware
The 30-year Treasury yield climbed above 5.3%, its highest level in 19 years. Micron fell 7%, while SanDisk and Seagate dropped about 9%. With AI hardware valued heavily on profits expected years into the future, rising long-term rates put immediate pressure on those valuations.
The AI Bill Is Getting Scrutiny
A Wall Street Journal review of filings found nine major technology firms carrying roughly $3 trillion of future AI commitments in their footnotes — about five times what they spent last year. As yields rise, the cost behind the massive AI buildout becomes increasingly important to investors.
The Pressure Spread Overseas
South Korea’s Kospi fell nearly 6% overnight and Japan’s Nikkei dropped about 3%, with Japan’s 10-year yield near a 30-year high. Yet the Dow slipped only about 0.2% and the Nasdaq lost 1.3%, pointing to concentrated pressure rather than a uniform market decline.
What Matters From Here
Yesterday explains what triggered the selloff. The more important question now is whether the forces behind it keep building.
- Can Micron and other AI hardware names stabilize if the 30-year Treasury yield remains above 5.3% or moves even higher?
- Will today’s July Federal Reserve minutes reinforce the rate pressure after three officials voted to raise rates at the meeting?
- Does Brent crude near $92 add another layer of pressure as Washington and Tehran clash over whether the Strait of Hormuz is open?
The Headlines Are Only the First Step
The free Market Preview explains why the AI hardware trade suddenly came under pressure. The members-only Daily Market Brief goes deeper into the catalysts, risks, confirmation signals, and developments that can help determine whether this remains a targeted rate-driven reset or begins changing the broader market setup.
See What Members GetInside Today’s Members-Only Daily Market Brief
- The Treasury-yield developments that could confirm whether pressure on rate-sensitive AI stocks is continuing or beginning to ease.
- What today’s Fed minutes could change after three officials voted in favor of raising rates at the July meeting.
- The signals that can help distinguish weakness concentrated in expensive AI hardware from deterioration spreading across the broader market.
- How the roughly $3 trillion of future AI commitments fits into the financing-cost story investors are now reassessing.
- The oil and Strait of Hormuz developments worth monitoring if Brent near $92 continues adding pressure to the market backdrop.
Go Beyond the Headlines
The public Market Preview tells you what happened and why investors are paying attention. The Generational Wealth Community is designed for investors who want to understand what deserves attention next, what could confirm the current setup, what risks could change it, and which developments deserve continued monitoring. We don’t chase hype, we decode the market.
Unlock the Daily Market BriefEducational market research designed to help investors understand the setup — not chase headlines.
Your pathway from knowledge to legacy. We don’t chase hype, we decode the market.
Stay Ahead of What Matters Next
Understand the catalysts, risks, and market signals that deserve continued attention as yields, AI spending, oil, and Federal Reserve policy reshape the setup.
Join the Generational Wealth Community
Hormuz Attacks Lift Oil and Gold as Stocks Near Records
Attacks around the Strait of Hormuz are keeping pressure on oil while gold holds near $4,400 and U.S. stocks remain just below record territory. See why markets are staying relatively calm—and what retail earnings and Fed minutes could change this week.
August 16, 2026
Market Preview: Hormuz Attacks Lift Oil and Gold as Stocks Near Records
The Strait of Hormuz is operating near seventeen percent of normal traffic, new attacks have added to the risk around global energy supplies, and yet U.S. stocks finished the week just below a record high. Oil, gold, inflation and interest-rate expectations are telling different parts of the story. Today’s video breaks down why markets remain relatively calm and what could challenge that view this week.
Watch Today’s Market Breakdown
Oil Tankers Under Attack, Gold at $4,400, Stocks Near Record — What Markets Know
Today’s Market Snapshot
Hormuz Risk Is Building
British maritime authorities reported a bulk carrier struck by a projectile Saturday, following three attacks on Abu Dhabi state oil tankers in forty-eight hours. Iran has also not decided whether to return to talks, keeping uncertainty around the world’s most important oil chokepoint elevated.
Markets Are Still Relatively Calm
U.S. stocks closed the week a fraction below a record high while volatility finished at its lowest level of the year. July inflation cooled for a second consecutive month to 3.4%, and traders placed roughly seven-in-ten odds on the Federal Reserve holding rates next month.
Oil and Gold Show the Pressure
U.S. crude settled Friday near $82 while gold held around $4,400 after gaining more than 10% in a month. Bitcoin, near $63,000, has not joined that move. Meanwhile, retail sales fell 0.6% in July and consumer sentiment declined to 51.
What Investors Should Be Watching
- Whether escalating developments around the Strait of Hormuz push energy prices higher or markets continue treating the disruption primarily as a price problem rather than a broader growth problem.
- What Home Depot on Tuesday, Target on Wednesday and Walmart on Thursday reveal about consumer spending after July retail sales declined.
- Whether Wednesday’s Federal Reserve minutes change rate expectations after three officials voted to raise rates at the meeting.
Inside Today’s Members-Only Daily Market Brief
- The market levels and catalysts that matter as stocks remain near record territory.
- The strongest and weakest areas of the market beneath the major indexes.
- The risks that could change the market’s current interpretation of energy and inflation.
- Important developments to monitor as retail earnings and the Fed minutes arrive.
- A clearer explanation of what today’s competing signals may mean for investors.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market BriefYour pathway from knowledge to legacy. We don’t chase hype, we decode the market.

Retail Sales Drop 0.6% as Small Caps Hit Record High
Retail sales fell 0.6% in July and consumer sentiment sank to 51, yet the Russell 2000 closed at an all-time high as rate-hike fears faded. The bond market disagreed — the ten-year yield rose to 4.68% while oil spiked near $82 on Strait of Hormuz tensions.
Market Preview: Retail Sales Fall 0.6% as Small Caps Close at a Record and Oil Spikes to $82
The American consumer just posted the biggest spending drop in more than a year — and small-cap stocks closed at an all-time high the same session. The bond market didn't go along with it: the ten-year yield rose instead of falling, while oil settled near $82 after drone strikes in the Strait of Hormuz. Today's video explains the tension underneath a record close: cheaper money versus more expensive energy.

Today's Market Snapshot
The Consumer Pulled Back
Retail sales fell six tenths of a percent in July, the biggest drop in more than a year, when economists had expected a small increase. Consumer sentiment sank about 8% to 51, and households now expect 4.3% inflation over the next year.
Small Caps Hit a Record Anyway
After softer inflation reports Wednesday and Thursday, a weaker consumer eased fears the Fed must raise rates again in September. Small caps are the most rate-sensitive corner of the market, and the Russell 2000 closed at an all-time high.
Bonds and Oil Disagreed
The ten-year Treasury yield rose to 4.68% instead of falling on weak data — a signal inflation risk hasn't gone away. Oil settled near $82, up more than 5% on the week after Strait of Hormuz tanker strikes. Energy led all sectors, up roughly 7%.
What Investors Should Be Watching
- The retailers deliver their own verdict this week — Home Depot Tuesday, Target and Lowe's Wednesday, Walmart Thursday. If they confirm shoppers are pulling back, that small-cap record gets much harder to defend.
- Whether the ten-year yield keeps climbing on soft data, which would say the bond market is more worried about inflation than about growth.
- Whether the Strait of Hormuz situation escalates or cools, with gasoline still around $4 a gallon and the naval blockade open-ended.
Inside Today's Members-Only Daily Market Brief
- The levels members are tracking on small caps now that the Russell 2000 is at a record with a weakening consumer underneath it.
- How to read a bond market that rises on bad news — and what that pattern has historically meant for rate expectations.
- What each retailer print this week would do to the September rate debate, and which one carries the most weight.
- Where the energy trade sits after a 7% sector week, and the risks that could reverse it quickly.
- The strongest and weakest areas of the market heading into the next session.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief
Oil's Biggest Build in 3.5 Years — And Prices Rose Anyway
U.S. crude inventories posted their biggest weekly build in three and a half years — 17.4 million barrels, against expectations for a drawdown — and oil closed higher anyway. Today's preview breaks down why the barrels piled up, what the Strait of Hormuz has to do with it, and why the Fed's next move may be a hike.
Market Preview: Oil Posts Its Biggest Build in 3.5 Years as Prices Climb Anyway
America's oil stockpile just posted its biggest weekly jump in three and a half years — 17.4 million barrels, when forecasters were looking for a drawdown — and crude still closed higher. That combination usually signals something other than weak demand. Today's video explains what the headline inventory number misses, and why it points toward the Federal Reserve.

Today's Market Snapshot
A Record Build, and a Higher Close
Government data showed U.S. crude inventories rose 17.4 million barrels in a single week, the largest build in three and a half years. Forecasters had expected a drawdown. Crude closed slightly higher anyway — the kind of divergence that says the inventory number is measuring something other than demand.
Hormuz Is the Bottleneck
American crude exports fell to their lowest level since the war with Iran began, while imports surged. Barrels piled up because they couldn't ship out. The Strait of Hormuz remains effectively closed, and the IEA now sees the world short roughly 1.8 million barrels a day this quarter.
Energy Reaches the Rate Path
July inflation cooled to 3.4%, but energy is still up nearly 15% from a year ago — which is why September odds now favor a hike near 42% rather than a cut. This morning crude finally cracked, with WTI near $81.60, down about 2%, snapping a five-day run on reopening-deal chatter.
What Investors Should Be Watching
- Wholesale inflation at 8:30 Eastern — the last read before September rate odds firm up, and the number most likely to move a hike-versus-cut debate that is already leaning one way.
- Whether talk of a deal to reopen the Strait of Hormuz can keep pressure on crude, or whether a shortfall the IEA puts near 1.8 million barrels a day reasserts itself.
- Whether the AI trade steadies after the S&P 500 closed at 7,748 on AI earnings, with Cerebras down roughly 17% before the bell — a sign the leadership may be narrowing.
Inside Today's Members-Only Daily Market Brief
- The specific crude levels members are tracking now that WTI has broken a five-day run, and what would confirm the move.
- Both sides of this morning's wholesale inflation print, and what each outcome does to a September decision priced near a coin flip.
- How to read an inventory build that reflects logistics rather than demand — and the tell that separates the two.
- What the shipping response signals about how long the Hormuz constraint is expected to last.
- Where capital is rotating as energy costs, not growth, become the pressure point on the rate path.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief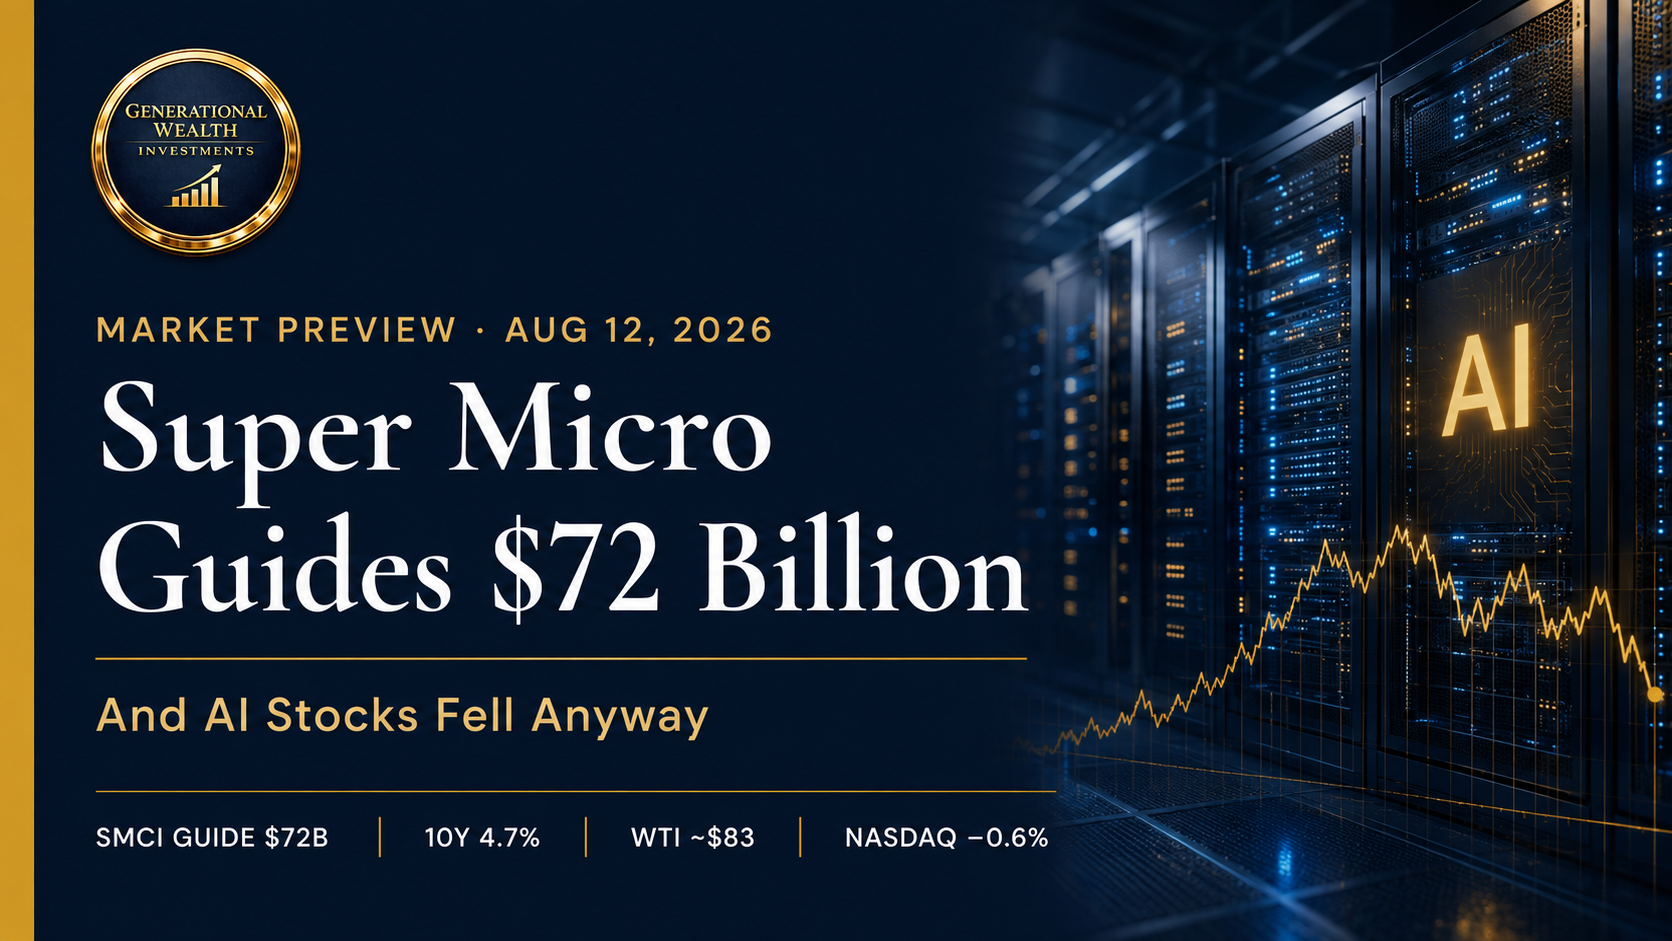
Super Micro Guides $72B as AI Stocks Sell Off Anyway
Super Micro guided to as much as $72 billion in AI server sales next year, roughly $19 billion above Wall Street's model, and the stock jumped about 9% after hours — hours after AI stocks had sold off all day. Today's preview decodes why the doubt has shifted from demand to financing, with yields near 4.7%, crude around $83, and the July inflation report landing at 8:30.
Market Preview: Super Micro Guides $72 Billion as AI Stocks Sell Off Anyway
Super Micro told Wall Street it expects to sell as much as $72 billion of AI servers next year — roughly $19 billion above what analysts were modeling — and the stock jumped about 9% after hours. The strange part is the timing: AI stocks had sold off all day in the regular session. Today's video explains why the doubt on Wall Street is no longer about demand, but about how the buildout gets paid for.

Today's Market Snapshot
Demand Beats, and Then Some
Super Micro guided to as much as $72 billion in AI server sales next year, against roughly $53 billion modeled on Wall Street. The stock rose about 9% after hours. CoreWeave said the same evening that its backlog grew roughly $25 billion in six weeks, and its stock jumped as well.
The Funding Question Takes Over
Hours earlier, AI names sold off all session. Alphabet fell nearly 4% on data center spending worries, Intel priced a $20 billion stock sale upsized from $15 billion, and Nvidia lined up more than $500 billion of outside financing this week. The Nasdaq closed down about 0.6%, a second straight loss.
Yields and Oil Set the Cost
When a buildout runs on borrowed money, the cost of borrowing becomes the story. The 10-year Treasury yield sits near 4.7%. Crude settled around $83, a fourth straight gain, after Iran said the Strait of Hormuz stays shut. Both feed directly into this morning's inflation math.
What Investors Should Be Watching
- The July inflation report at 8:30 this morning, where economists expect headline inflation around 3.4% — a cooler number takes pressure off yields, a hotter one makes every one of these deals pricier.
- Whether the after-hours enthusiasm around Super Micro and CoreWeave carries into the regular session, or whether the financing questions reassert themselves the way they did Tuesday.
- Whether crude can extend a fourth straight gain with the Strait of Hormuz still closed, and what that does to the rate path traders are already pricing near a coin flip for a hike.
Inside Today's Members-Only Daily Market Brief
- The specific levels members are tracking across the 10-year, crude, and the AI complex as the funding story develops.
- Both sides of this morning's inflation print, and what each outcome would mean for a rate decision now priced near even.
- Why the market can sell a demand beat, and what would actually resolve the question of who is holding the paper.
- How the Intel and Nvidia financing structures differ, and which one tells you more about the cycle.
- Where capital is rotating as borrowing costs, not demand, become the constraint on the buildout.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief
Nvidia's $500B AI War Chest as Oil Surges | Aug 11, 2026
Nvidia lined up more than $500 billion from six Wall Street giants for AI data centers, and the stock fell anyway on circular financing concerns. Crude surged roughly 5% as Hormuz talks stalled, the 10-year yield topped 4.7%, and September rate hike odds moved to roughly even ahead of Wednesday's CPI.
Market Preview: Nvidia Lines Up $500 Billion for AI as Oil Surges and Rate Hike Odds Climb
Nvidia announced partnerships with six of the largest firms on Wall Street to mobilize more than $500 billion for AI data centers — and the stock fell anyway. Meanwhile crude jumped roughly 5%, the 10-year Treasury yield pushed above 4.7%, and traders now put roughly even odds on a Federal Reserve rate hike in September. Today's video connects the energy move, the AI financing question, and the rate math heading into Wednesday's inflation print.

Today's Market Snapshot
Crude Jumps as Hormuz Talks Stall
West Texas Intermediate settled up about 5% Monday near $82 a barrel, with Brent near $88, after President Trump demanded Iran pay compensation and talks to reopen the Strait of Hormuz stalled. Both moved higher again this morning, Brent near its highest since late July. Producers and refiners benefit if it holds.
Nvidia's $500 Billion Question
Nvidia announced partnerships with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to mobilize over $500 billion for AI data centers. Shares still fell roughly 2–3% as investors questioned circular financing, recovering slightly overnight. Intel dropped nearly 4% on a $15 billion dilutive stock offering.
Yields Rise, Stocks Slip
Higher oil lifted inflation expectations and the 10-year Treasury yield climbed above 4.7%, near its highest since January. September hike odds moved to roughly even from about 44% Monday, and Cleveland Fed President Hammack said several increases may be needed. The S&P 500 closed down 0.1% at 7,752.
What Investors Should Be Watching
- Wednesday's consumer price index, now the week's real catalyst after oil and yields reset expectations for the September meeting.
- Whether AI spending confirmation arrives, with CoreWeave reporting today and Applied Materials Thursday — or whether the financing questions around Nvidia's announcement keep pressure on leadership.
- Whether the crude rally holds, and what a sudden deal reopening the Strait of Hormuz would do to the energy trade.
Inside Today's Members-Only Daily Market Brief
- The specific levels and catalysts members are tracking across crude, gold, and rates as the Hormuz standoff drags on.
- Both sides of Wednesday's inflation print, and what each outcome would mean for a September hike now priced near a coin flip.
- Why circular financing is drawing scrutiny, and what would actually confirm or break the AI spending story this week.
- The bitcoin level analysts say shifts sentiment, plus what recent fund flows suggest beneath a heavy tape.
- Where capital is rotating as money moves toward energy and hard assets while AI leadership wobbles.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief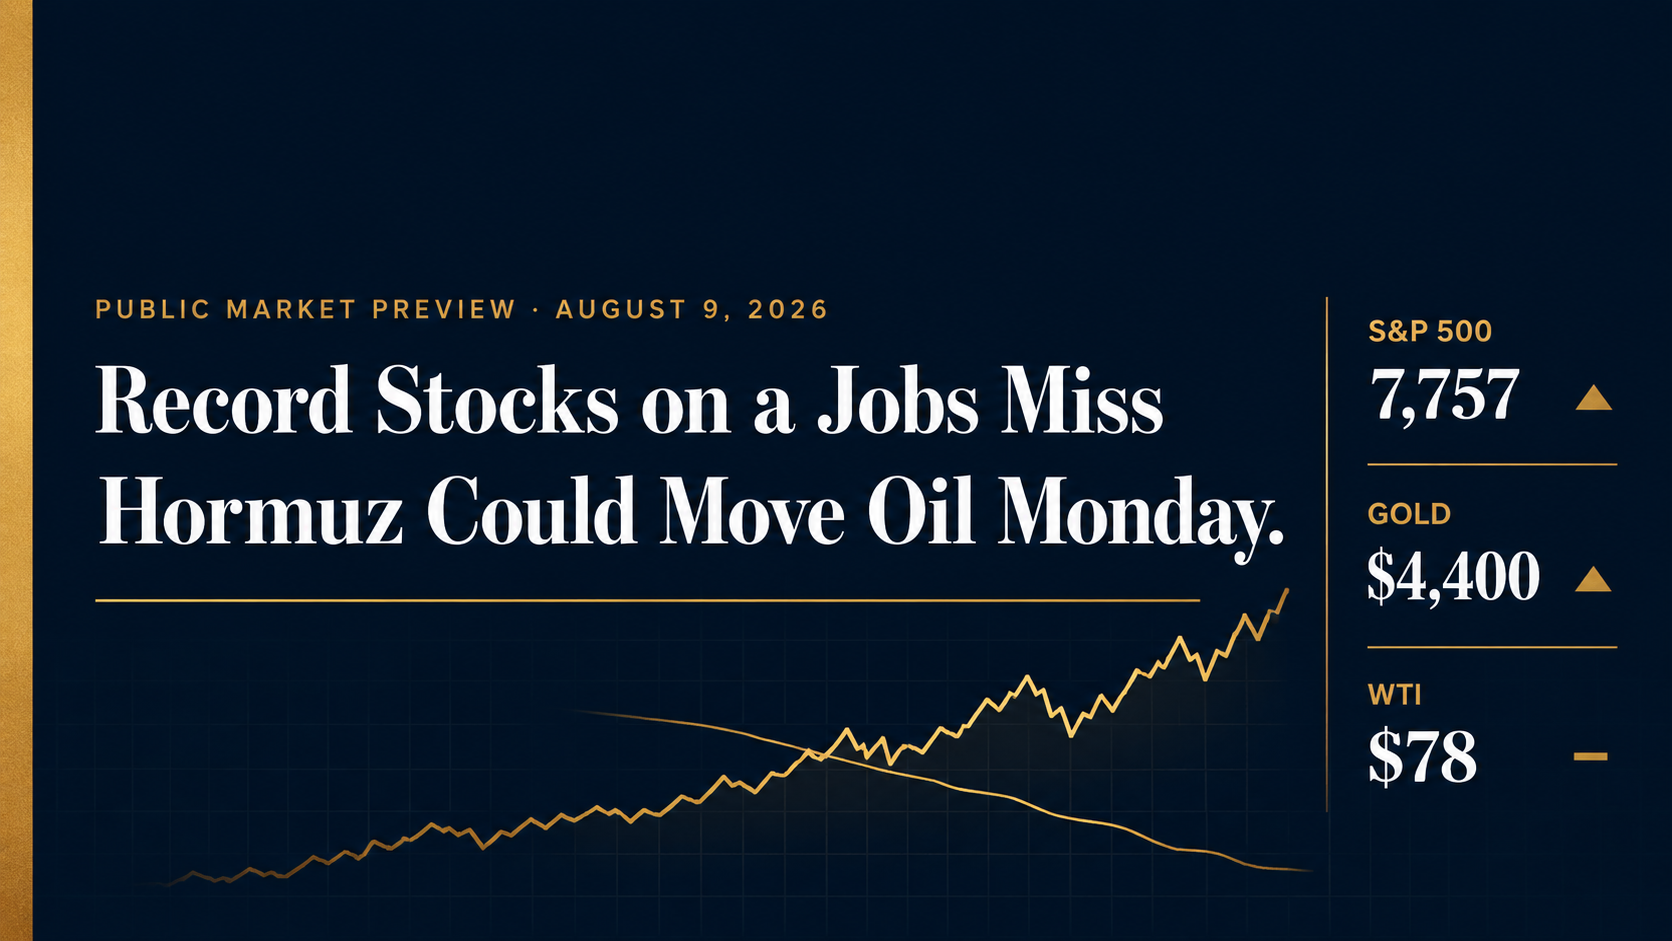
Market Preview: Record Stocks, Jobs Miss, Hormuz Oil Risk
The U.S. economy lost 23,000 jobs in July and the S&P 500 still closed at a record 7,757, as investors read the miss as taking a September rate hike off the table. Today's preview covers the software rotation, gold's seven-week high, and the Strait of Hormuz headlines that could move oil Monday.
Market Preview: Stocks Close at Records on a Jobs Miss as Strait of Hormuz Headlines Could Move Oil Monday
The economy lost jobs in July and equities finished Friday at a record anyway — investors read the miss as taking a September rate hike off the table. That repricing landed hardest in software, where one name closed up roughly 35%. Meanwhile, weekend developments around the Strait of Hormuz set up energy markets for a live Monday. Today's video walks through what connects all three.

Today's Market Snapshot
Jobs Data Resets the Rate Path
July payrolls fell by 23,000 against expectations for a gain near 80,000, while unemployment ticked down to 4.1%. Investors read that as taking a September hike off the table. The S&P 500 closed at a record 7,757, the Nasdaq added 1.3% to 26,690, and the 10-year yield eased to about 4.66%.
Software Leads as Money Rotates
Atlassian closed up roughly 35% after 28% revenue growth and beat guidance. Twilio rose about 27% and Cloudflare about 9%, while Nvidia gained more than 11% on the week. Capital appears to be rotating toward growth and AI names; energy shares lagged even as crude rose.
Oil, Gold, and Crypto Flows
Iran said it is close to a navigation deal with Oman, but its foreign minister warned that alone would not reopen the Strait of Hormuz. WTI settled near $78. December gold settled near $4,400, a seven-week high. Bitcoin held near $64,900 as spot funds took in over $750 million last week.
What Investors Should Be Watching
- Wednesday's July inflation report. A hot print would revive hike talk and challenge the rate math that drove Friday's record close.
- Whether the Hormuz situation moves toward a genuine reopening or a breakdown in talks — one path eases energy costs, the other does the opposite.
- Whether the software and AI rotation broadens, with cloud guidance holding up as the confirmation traders are looking for.
Inside Today's Members-Only Daily Market Brief
- The specific levels and catalysts members are tracking across gold, oil, and the September rate path.
- Both sides of Wednesday's inflation print, plus what to monitor around Cisco, CoreWeave, and Applied Materials earnings.
- Where capital is rotating as money moves out of energy and into growth and AI names — the strongest and weakest areas of the tape.
- What the divergence in crypto fund flows may be signaling, including the collapse in XRP inflows against steady bitcoin demand.
- The risks that could reverse a record week, and why a seven-week high in gold may still read as recovery rather than breakout.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief
Oil Spikes on Hormuz Plan as Gold Nears Best Week Since Jan
A single Iranian document on Strait of Hormuz shipping sent Brent up 3.8%, pushed the 10-year yield above 4.67%, and ended the Dow's record streak — while gold ran to its best week since January. Today's preview covers the memory chip selloff, where capital is rotating, and what the July jobs report could change.
Two things worth flagging: the snapshot figures are session-specific and will read stale within a day or two, so if you want this page to have a longer shelf life on the blog, say the word and I'll swap in an evergreen variant. And if you want the header banner and social thumbnail assets to match, I can build those next.
Market Preview: Oil Spikes on a Hormuz Document as Gold Heads for Its Best Week Since January
Iranian state media published a draft plan restricting ship traffic through the Strait of Hormuz, and Brent settled up about 3.8% — reversing a week of steep declines. Higher energy costs pushed the 10-year yield above 4.67% and lifted September Fed rate hike odds to roughly 58%, ending the Dow's record streak. Today's video breaks down why memory chip stocks sold off despite strong results, and why gold is having its best week since January.

Today's Market Snapshot
Energy and Rates: One Document Moves Everything
Iranian state media published a draft plan restricting Strait of Hormuz ship traffic. Brent settled up roughly 3.8% near $82.49 and WTI near $77.29, reversing a week of steep declines. Higher energy costs fed inflation expectations: the 10-year Treasury yield climbed more than five basis points to about 4.67%, and September rate hike odds sit near 58%.
Equities: Memory Chips Break the Record Streak
The Dow fell 464 points, or 0.85%, to 53,885, ending its record run. The S&P 500 slipped just under 7,710 and the Nasdaq was nearly flat. Western Digital dropped about 13% and SanDisk near 7% despite both beating results — guidance disappointed. Selling spread to Asia, where SK Hynix fell sharply. AppLovin tumbled roughly 19%.
Metals and Crypto: Rotation Into Hard Assets
Gold traded near $4,254 an ounce, up roughly 5% on the week and on pace for its best week since January, with silver around $62. Crypto stayed quiet: Bitcoin near $64,700 and still capped below $65,000, Ether near $1,910, XRP around $1.03. Cardano was the standout, up about 6.5%.
What Investors Should Be Watching
- The July jobs report at 8:30 a.m. Eastern. Economists expect roughly 80,000 jobs after 57,000 in June, with unemployment near 4.2%. A hot print strengthens the September hike case; a weak one does the opposite.
- Whether the memory chip selling stays contained. Western Digital grew revenue about 44% and still fell 13%, which suggests investors are repricing how much AI growth is already built into these names.
- Whether the Hormuz restrictions hold. The move in oil came from a published draft plan, and crude, yields and gold all reprice quickly if that story changes direction again.
Inside Today's Members-Only Daily Market Brief
- The specific levels and catalysts members are tracking across crude, gold and the 10-year as rate hike odds climb toward 58%.
- How members are reading the memory chip selloff, including the confirmation signal that would tell us whether this is sector-specific or the start of a broader AI valuation reset.
- Where capital is rotating as money moves out of crowded AI trades and into rate-sensitive and hard assets — the strongest and weakest areas of the tape.
- The risks that could reverse a 5% weekly move in gold, and why chasing a sharp run carries added risk.
- Both sides of the July jobs report, and what to monitor into the next session depending on which way the number lands.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief