


Retail Sales Drop 0.6% as Small Caps Hit Record High
Retail sales fell 0.6% in July and consumer sentiment sank to 51, yet the Russell 2000 closed at an all-time high as rate-hike fears faded. The bond market disagreed — the ten-year yield rose to 4.68% while oil spiked near $82 on Strait of Hormuz tensions.
Market Preview: Retail Sales Fall 0.6% as Small Caps Close at a Record and Oil Spikes to $82
The American consumer just posted the biggest spending drop in more than a year — and small-cap stocks closed at an all-time high the same session. The bond market didn't go along with it: the ten-year yield rose instead of falling, while oil settled near $82 after drone strikes in the Strait of Hormuz. Today's video explains the tension underneath a record close: cheaper money versus more expensive energy.

Today's Market Snapshot
The Consumer Pulled Back
Retail sales fell six tenths of a percent in July, the biggest drop in more than a year, when economists had expected a small increase. Consumer sentiment sank about 8% to 51, and households now expect 4.3% inflation over the next year.
Small Caps Hit a Record Anyway
After softer inflation reports Wednesday and Thursday, a weaker consumer eased fears the Fed must raise rates again in September. Small caps are the most rate-sensitive corner of the market, and the Russell 2000 closed at an all-time high.
Bonds and Oil Disagreed
The ten-year Treasury yield rose to 4.68% instead of falling on weak data — a signal inflation risk hasn't gone away. Oil settled near $82, up more than 5% on the week after Strait of Hormuz tanker strikes. Energy led all sectors, up roughly 7%.
What Investors Should Be Watching
- The retailers deliver their own verdict this week — Home Depot Tuesday, Target and Lowe's Wednesday, Walmart Thursday. If they confirm shoppers are pulling back, that small-cap record gets much harder to defend.
- Whether the ten-year yield keeps climbing on soft data, which would say the bond market is more worried about inflation than about growth.
- Whether the Strait of Hormuz situation escalates or cools, with gasoline still around $4 a gallon and the naval blockade open-ended.
Inside Today's Members-Only Daily Market Brief
- The levels members are tracking on small caps now that the Russell 2000 is at a record with a weakening consumer underneath it.
- How to read a bond market that rises on bad news — and what that pattern has historically meant for rate expectations.
- What each retailer print this week would do to the September rate debate, and which one carries the most weight.
- Where the energy trade sits after a 7% sector week, and the risks that could reverse it quickly.
- The strongest and weakest areas of the market heading into the next session.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief
Applied Materials Falls on Margins as S&P 500 Hits Record
Applied Materials posted the biggest quarter-to-quarter revenue jump in its history and the stock fell about 5% anyway — the second straight day a beat-and-raise was punished over margins. Today's preview breaks down what that pattern says about the AI trade, and why the S&P 500 still closed at a record.
Market Preview: Applied Materials Posts Record Revenue and Drops Anyway as the S&P 500 Closes at a High
Applied Materials just reported the biggest quarter-to-quarter revenue jump in its history — and the stock fell about 5% after hours. That's two days running where a company beat, raised guidance, and sold off anyway, and both times the market pointed at the same line item. Today's video explains what margins are saying about the AI trade, and why the index closed at a record regardless.

Today's Market Snapshot
Record Revenue, Falling Stock
Applied Materials posted record revenue just over $9 billion, up 25% from a year ago, beat on earnings, and raised its outlook. The stock still fell about 5% after hours. Management guided to flat gross margins next quarter, and that single line outweighed everything else in the report.
Two Days, Same Story
Cisco beat and guided above estimates, then dropped 8.4% Thursday. Analysts kept returning to margins: gross margin slipped to roughly 66% from 68%, partly because the memory inside AI hardware has grown more expensive. Investors aren't questioning AI demand — they're questioning what it costs to meet it.
The Index Barely Blinked
Micron, which sells that memory, rose more than 4% the same day — the cost is moving through the AI trade, not ending it. Meanwhile the S&P 500 closed at a record just under 7,800 after wholesale inflation came in flat for July and traders trimmed September rate-hike odds.
What Investors Should Be Watching
- July retail sales at 8:30 Eastern — the read on the consumer landing right after a flat wholesale inflation print already pulled September rate-hike odds lower.
- The SEC votes at 10 on its first formal crypto rulemaking, with Bitcoin near $63,000.
- Whether the Applied Materials drop holds at the open, or whether buyers treat a margin warning inside record revenue differently in daylight.
Inside Today's Members-Only Daily Market Brief
- The levels members are tracking on Applied Materials as an after-hours drop meets the cash open.
- How to read a margin squeeze that travels through the AI supply chain — and which side of it is absorbing the cost.
- What each retail sales outcome would do to September rate expectations now that a hike has been trimmed back.
- Why the SEC's first formal crypto rulemaking deserves attention beyond today's headline.
- Where the strongest and weakest parts of the market sit with the index at a record.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief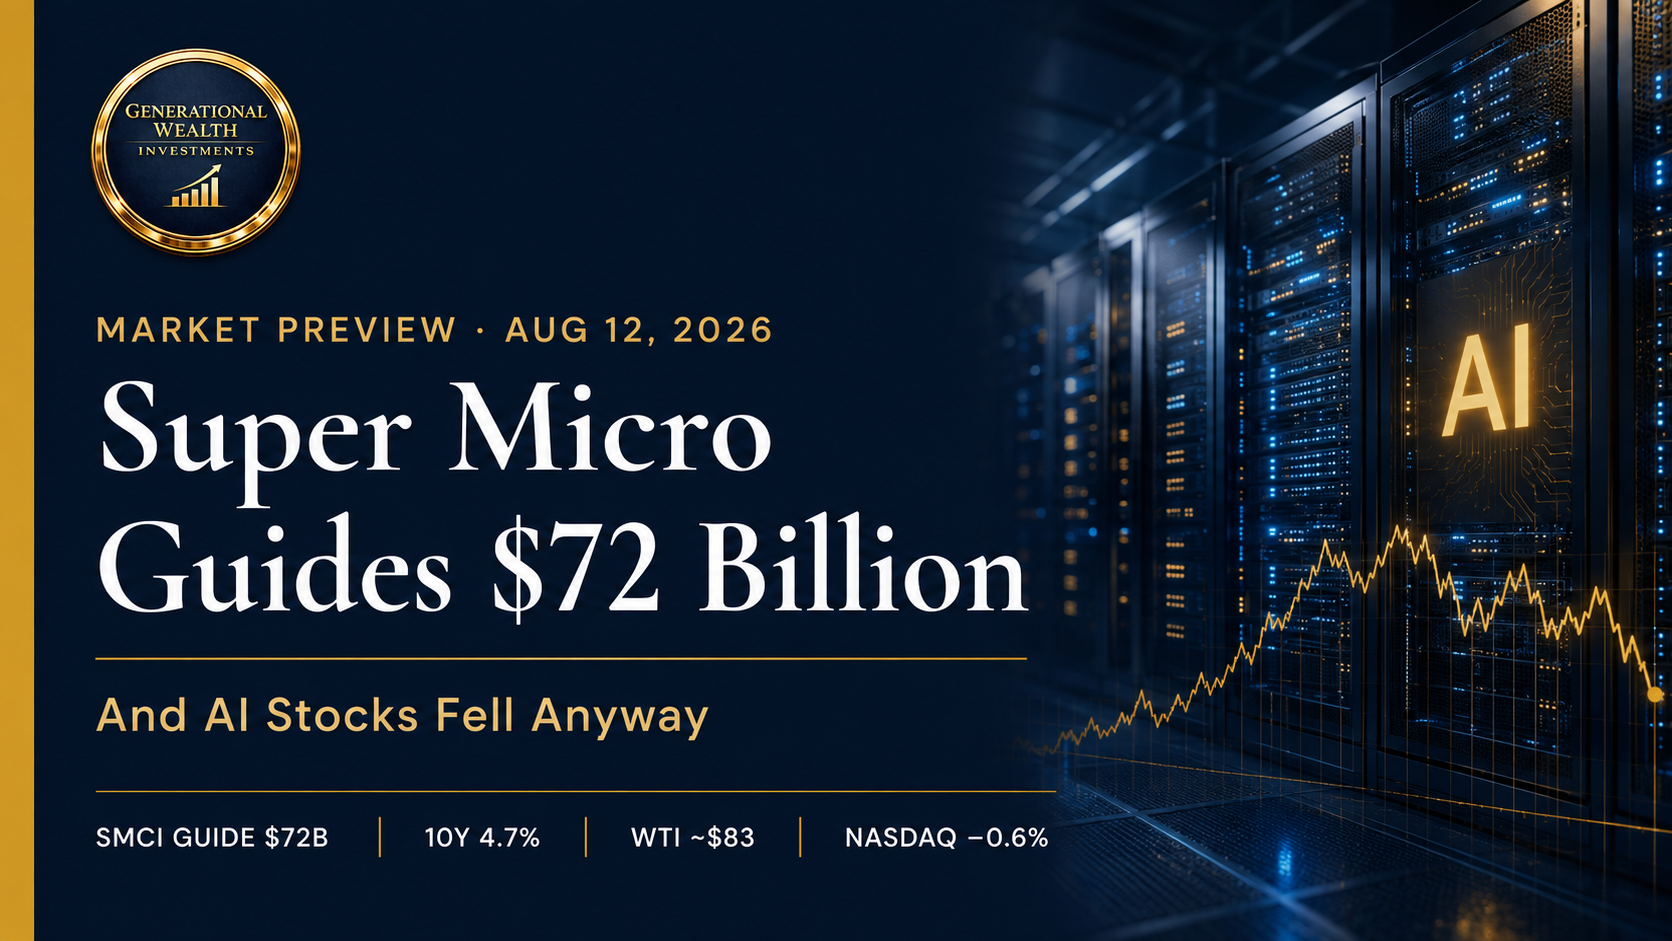
Super Micro Guides $72B as AI Stocks Sell Off Anyway
Super Micro guided to as much as $72 billion in AI server sales next year, roughly $19 billion above Wall Street's model, and the stock jumped about 9% after hours — hours after AI stocks had sold off all day. Today's preview decodes why the doubt has shifted from demand to financing, with yields near 4.7%, crude around $83, and the July inflation report landing at 8:30.
Market Preview: Super Micro Guides $72 Billion as AI Stocks Sell Off Anyway
Super Micro told Wall Street it expects to sell as much as $72 billion of AI servers next year — roughly $19 billion above what analysts were modeling — and the stock jumped about 9% after hours. The strange part is the timing: AI stocks had sold off all day in the regular session. Today's video explains why the doubt on Wall Street is no longer about demand, but about how the buildout gets paid for.

Today's Market Snapshot
Demand Beats, and Then Some
Super Micro guided to as much as $72 billion in AI server sales next year, against roughly $53 billion modeled on Wall Street. The stock rose about 9% after hours. CoreWeave said the same evening that its backlog grew roughly $25 billion in six weeks, and its stock jumped as well.
The Funding Question Takes Over
Hours earlier, AI names sold off all session. Alphabet fell nearly 4% on data center spending worries, Intel priced a $20 billion stock sale upsized from $15 billion, and Nvidia lined up more than $500 billion of outside financing this week. The Nasdaq closed down about 0.6%, a second straight loss.
Yields and Oil Set the Cost
When a buildout runs on borrowed money, the cost of borrowing becomes the story. The 10-year Treasury yield sits near 4.7%. Crude settled around $83, a fourth straight gain, after Iran said the Strait of Hormuz stays shut. Both feed directly into this morning's inflation math.
What Investors Should Be Watching
- The July inflation report at 8:30 this morning, where economists expect headline inflation around 3.4% — a cooler number takes pressure off yields, a hotter one makes every one of these deals pricier.
- Whether the after-hours enthusiasm around Super Micro and CoreWeave carries into the regular session, or whether the financing questions reassert themselves the way they did Tuesday.
- Whether crude can extend a fourth straight gain with the Strait of Hormuz still closed, and what that does to the rate path traders are already pricing near a coin flip for a hike.
Inside Today's Members-Only Daily Market Brief
- The specific levels members are tracking across the 10-year, crude, and the AI complex as the funding story develops.
- Both sides of this morning's inflation print, and what each outcome would mean for a rate decision now priced near even.
- Why the market can sell a demand beat, and what would actually resolve the question of who is holding the paper.
- How the Intel and Nvidia financing structures differ, and which one tells you more about the cycle.
- Where capital is rotating as borrowing costs, not demand, become the constraint on the buildout.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief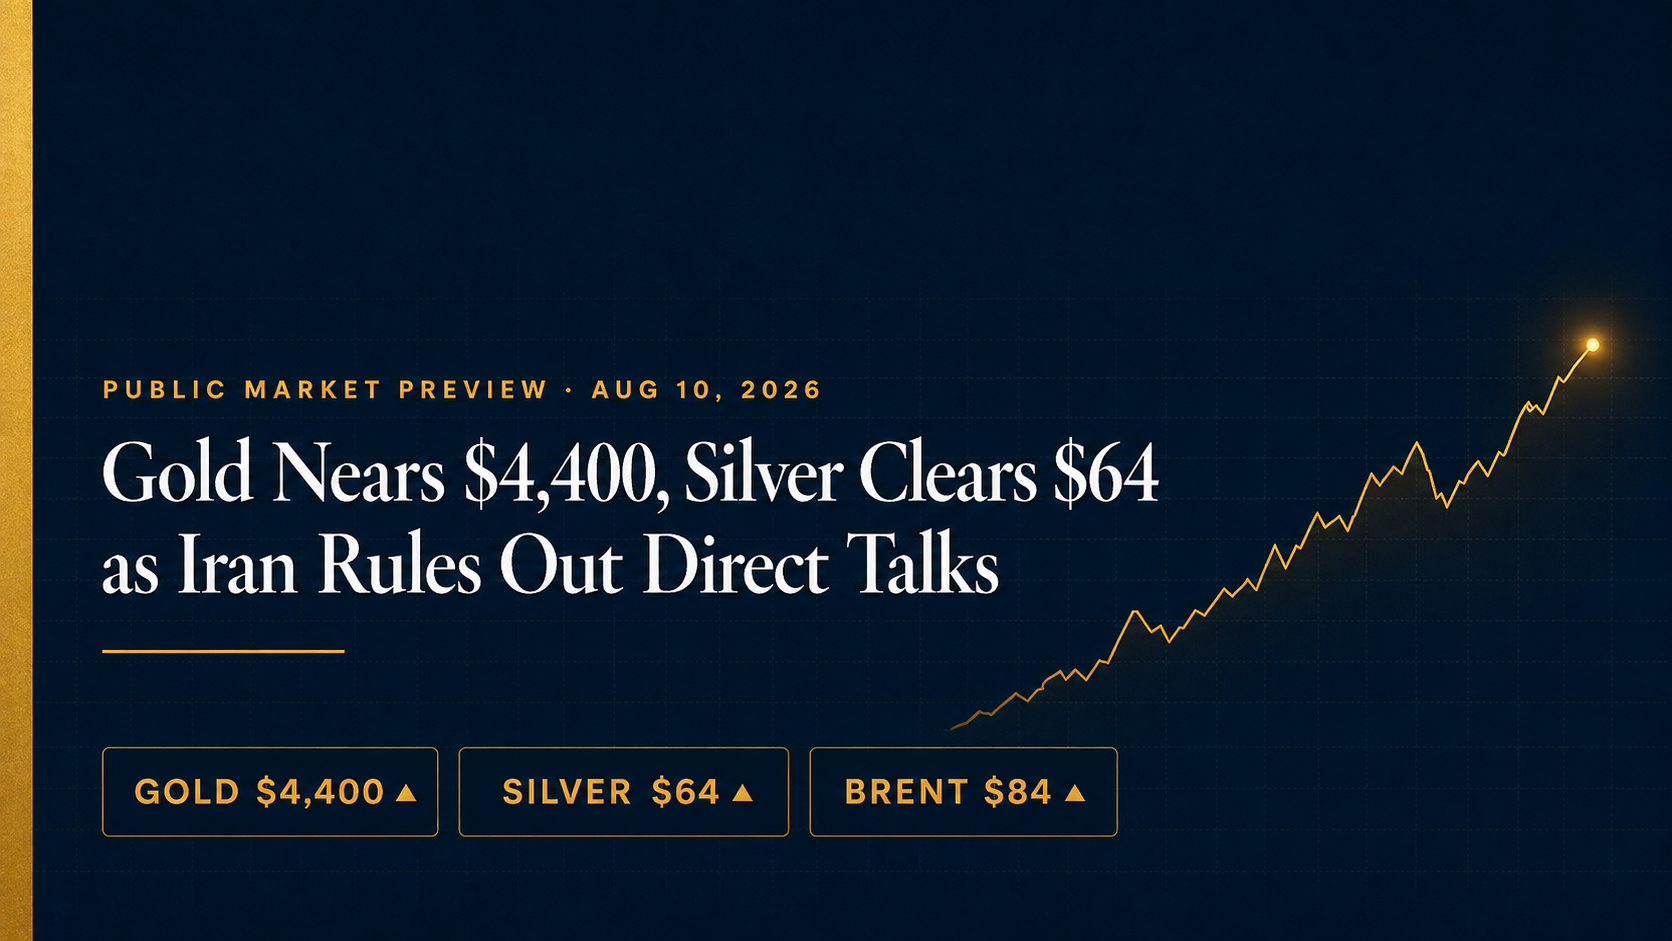
Gold Nears $4,400, Silver Tops $64 as Iran Rules Out Talks
Iran ruled out direct talks with Washington and warned the Strait of Hormuz stays closed without U.S. concessions, sending crude higher for a third straight session and pushing gold toward $4,400 and silver past $64. Today's preview covers the metals move, Friday's record close, and what Wednesday's inflation print could change.
Market Preview: Gold Nears $4,400 and Silver Clears $64 as Iran Rules Out Direct Talks
Iran said Sunday it is not negotiating directly with Washington and that the Strait of Hormuz stays closed without U.S. concessions — and crude climbed for a third straight session. That uncertainty is pushing money into hard assets, with gold near $4,400 and silver up roughly 11% on the week, even as Nasdaq futures lead again ahead of Wednesday's inflation print. Today's video connects the geopolitics, the metals move, and the rate math.

Today's Market Snapshot
Iran Standoff Lifts Crude
Iran's foreign minister said Sunday that Tehran is not in direct negotiations with the United States, and warned the Strait of Hormuz will not reopen without American concessions. Brent for October traded just above $84 overnight, up roughly 0.8%, while WTI held near $79. A confirmed Iran–Oman shipping agreement is the main risk to the move.
Gold and Silver Push Higher
Gold futures traded around $4,400 an ounce overnight, with spot nearer $4,300. Silver pushed past $64, up roughly 11% over the past week. Miners and metals funds could benefit if the move holds — the open question is whether silver can defend its breakout on the first real pullback.
Records, Futures, and Flows
The S&P 500 closed Friday at a record 7,757, up 0.6%, and the Nasdaq Composite added 1.3% for its best week since April after July payrolls fell 23,000. Overnight, Nasdaq futures gained about 0.5% while Dow futures slipped. The Nikkei closed up near 2%; bitcoin held around $65,000.
What Investors Should Be Watching
- Wednesday's July consumer price report, expected near 3.4%. A surprise in either direction would reset the rate math that drove Friday's record close.
- Whether Iran and Oman confirm a shipping agreement, which would return barrels quickly and cut against the crude rally — or whether the standoff hardens instead.
- Whether the rotation into hard assets and AI hardware broadens, with CoreWeave and Super Micro reporting Tuesday and Applied Materials Thursday.
Inside Today's Members-Only Daily Market Brief
- The specific levels and catalysts members are tracking across gold, silver, and crude as the Hormuz standoff drags on.
- Both sides of Wednesday's inflation print, and what each outcome would mean for the September rate path.
- Where capital is rotating as money moves into hard assets and AI hardware while crude-sensitive cyclicals lag.
- What the Bank of Japan's July meeting summary signals for a September move — and why a sharply stronger yen is the risk to Tokyo's rally.
- What steady bitcoin ETF inflows and lagging XRP may be signaling beneath a quiet week in crypto.
Go Beyond the Headlines
The public video explains what happened. The Generational Wealth Community helps members understand what matters next, where the risks are, and which developments deserve continued attention.
Unlock the Daily Market Brief